The short answer: a high salary doesn't get anyone out of debt on its own. When student loans, taxes and a lifestyle that rose with every raise claim most of each paycheck, paying every bill on time can leave you right where you were a year ago. What changes that is a plan: knowing which balance to retire first and how much monthly room each payoff frees. Paying your monthly bills and having a strategy to eliminate your debt are two different things.
Illustrative examples throughout, except the reported case, which is from KPRC 2.
Why can a $250,000 salary still feel like running in place?
Take an illustrative young lawyer.
Four years of undergrad. Three hard years of law school. The bar exam. Seven years of putting life on hold, and six figures of student loans to show for it.
Then he makes it: a Big Law job paying $250,000 a year.
On paper, he should be set. But month after month, he's still carrying debt. He has a top-tier salary and one of the most prestigious jobs in the country, and it feels like running in place just to stay afloat.
Between the cost of becoming a lawyer, the pressure to live like one and the obligations that pile up along the way, even a big income can leave someone struggling to get ahead.
Why don't you hear about it?
On LinkedIn, lawyers announce new positions, promotions and career milestones. Almost nobody posts that they're struggling to keep up with their student loan payments.
That makes sense. When your professional identity rests on your reputation, admitting money trouble can feel like admitting you've failed.
Go to anonymous forums like Reddit, where nobody's name is attached, and you see the other side. Six-figure student loan balances. Strong salaries. Professionals who did everything they were supposed to do and still can't get ahead.
If that sounds familiar, the paycheck may not be the problem. A high income and financial freedom are two very different things.
The loan comes with it.
I'm excited to share that I'm starting a new position as an attorney!
new position
What does a real case look like?
In April 2026, KPRC 2 in Houston reported that a Harris County judge had filed for Chapter 13 bankruptcy in May 2025. The filing listed nearly $70,000 in debt. More than $30,000 of it was owed to American Express, with Chase, Discover and Bank of America among the other creditors.
A judge in his position earns about $175,000 a year, according to the Texas Tribune's government salary database.
The court dismissed the case in June 2025.
We don't know his full circumstances, and this isn't a judgment of him. It's public reporting, used here for education. But it raises a fair question: how does someone in a respected, well-paid public role end up owing tens of thousands of dollars to credit card companies?
Nearly $70,000 in debt.
 Original reporting
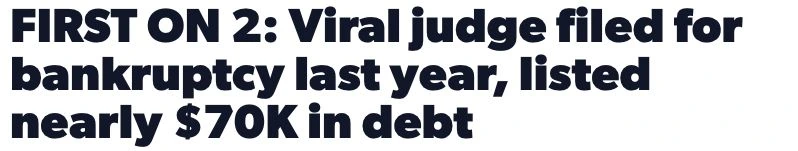 FIRST ON 2: Viral judge filed for bankruptcy last year, listed nearly $70K in debt
April 2, 2026 · KPRC 2 / Click2Houston
- May 2025Chapter 13 filed
- June 2025Case dismissed
- April 2026Public reporting
More than $30,000 owed to American Express.
Texas Tribune, July 1, 2026. A later snapshot, not salary at filing.
Headline from KPRC 2. The case was filed in 2025 and reported in 2026. We don't know his full financial picture.
Why do high earners struggle with debt?
There isn't one reason. Three things can stack up, little by little.
Nobody teaches it. Seven years of school taught our lawyer how to practice law. Very little of it covered managing cash flow, understanding debt or what borrowing really costs. He graduates, lands the job and starts collecting a paycheck, and the money is his to figure out alone.
Income gets all the attention. The path we're taught is a good education, a high-paying job and a steady climb up the income ladder. Income matters. But it's one side of the equation.
As a W-2 employee, a raise from $200,000 to $250,000 doesn't put another $50,000 in your account. Taxes take a portion first. And if spending rises with income, the raise does far less than it promised. You can earn more every year and barely move your debt.
Debts get treated like bills. That one takes a closer look.
What's the difference between a debt and an expense?
It's easy to see your finances as one list of monthly bills: the mortgage, the student loans, the car payment, the credit cards and everything else.
But they don't all work the same way.
When you pay for groceries or electricity, that money is gone. You paid for something you used.
A loan payment is different. There's a balance you still owe, and the monthly payment is what you're required to send toward it. Part of that payment may go to interest. Part goes to the balance.
This is where it's easy to get stuck. Making the required payment can feel like doing everything you need to do. Some people even see extra payments as a mistake, since that money could stay in the bank.
But the longer you carry a debt, the more interest you generally pay. Extra principal payments can cut that interest and clear the debt sooner, depending on the loan's terms. That doesn't mean every spare dollar should go to debt. Keep emergency savings and your other priorities in view.
The point is this. Paying your monthly bills and having a strategy to eliminate your debt are two different things.
You can earn $250,000, pay everything on time and still carry hundreds of thousands of dollars in debt, because the focus stays on making the payments instead of bringing the balances down efficiently.
If your income is already strong, the next gain may not come from earning more. It may come from using what you already earn more deliberately.
Is the balance coming down?
ElectricityPaid this month
You paid for what you used.
Next month brings new costs.
A payment covers interest
and reduces what you owe.
One-month illustration using the article's card: $30,000 at 30% APR, with a $1,050 payment. Interest is simplified as APR / 12, before payment. No new purchases or fees. Extra principal reduces the balance; it does not automatically remove the required payment.
How does the Cash Flow Index rank your debts?
The Cash Flow Index compares what you owe on a debt with its required monthly payment. Divide the balance by the payment.
The lower the number, the more monthly cash a payoff frees relative to what it takes to clear the debt. In the method, a score below 50 marks a debt worth a closer look.
Here's an illustrative comparison:
you look at first?
Balance / Required monthly payment = Cash Flow Index
Lower means less balance to retire per dollar of monthly payment.
Each block = $30,000 of balance
The card takes one-tenth as much to clear and removes $1,050 a month in payments, versus about $1,996 for the mortgage.
| Debt | Balance | Monthly payment | Index |
|---|---|---|---|
| Card · 30% | $30,000 | $1,050 | 28.6 |
| Mortgage · 7%, 30 years | $300,000 | About $1,996 | About 150 |
Illustrative figures, not market rates. Mortgage payment is principal and interest only. The index is a comparison of payment burden, not an APR, payoff timeline or interest-savings estimate. Avondale uses below 50 to flag a debt for closer review.
Paying off the card takes $30,000 and frees $1,050 a month. Paying off the mortgage takes $300,000 to free about $1,996 a month.
The card frees a large payment with one-tenth of the money. From a cash-flow view, that makes it worth examining first.
The index is one tool. Interest rates, total interest costs, your savings and your other priorities all matter when you decide which debt to tackle first.
What does this have to do with the judge's case?
We can't know what led to his filing, or whether any tool would have changed it.
What the index shows in general is this. When several debts each demand a large monthly payment, like credit cards with steep minimums, a paycheck can be spoken for before it lands, whatever the salary.
That's why the order you pay debts in matters, along with the total you owe. The more efficiently your income brings the balances down, the sooner monthly room comes back.
What's the honest part?
This isn't only a lawyer problem.
It's easy for anyone to run their money on one rule: keep the checking account in the green by the end of the month. As long as the bills are paid and there's money left, it feels like you're doing fine.
But money left in checking doesn't mean you're making progress.
You could earn a great income, make every payment on time and still owe almost as much as you did a year ago. You could be paying thousands of dollars in interest without ever adding it up.
And when the focus is getting through the month, the more important question never gets asked: is there a better way to use the money I'm already earning?
Your next step
Sit down with your numbers and do the exercise yourself. The free Debt Clarity Workbook puts every income source, every fixed and variable cost, and every debt with its Cash Flow Index in one view.
It won't tell you what to do. It'll show you which debts are actually squeezing your month. Set aside about thirty minutes. Get the free Debt Clarity Workbook.
And if you'd rather work through it with someone who does this every day, apply for a free first call. 15 minutes, no fee.
Sources: KPRC 2, "First on 2: Viral judge filed for bankruptcy last year, listed nearly $70K in debt," April 2, 2026, https://www.click2houston.com/news/local/2026/04/02/first-on-2-viral-judge-filed-for-bankruptcy-last-year-listed-nearly-70k-in-debt/ · The Texas Tribune, Government Salaries Explorer, https://salaries.texastribune.org/
Illustrative examples throughout, except the reported case, which is from KPRC 2. Figures are for illustration and are not predictions of individual results. Educational content only. This does not constitute financial, tax, or legal advice.