The short answer: when you work for yourself, the costs and risks an employer used to carry become yours: the taxes nobody withheld, both halves of Social Security and Medicare, your own insurance and retirement, the months you don't bill, and every obligation of the business. Lenders see it too. The bank works from income it can document, with the adjustments its lending rules allow. So the deductions that lower your tax bill can also lower what you can borrow. None of that is a reason to stop working for yourself. It's a reason to know what's actually yours before you spend it.
Illustrative examples throughout, except the reported case, which is from Hawaii News Now.
Why does the bank treat a W-2 paycheck differently?
Being your own boss is supposed to be the American dream. You set your hours, choose your clients and control your income.
Now consider two people who both believe they take home $100,000 a year. One is a W-2 employee. The other is self-employed. Both apply for a mortgage.
The employee usually documents income with recent pay stubs and W-2s. The hard part already happened before the check cleared:
- Federal and state income taxes were withheld.
- Social Security and Medicare were taken out.
- Health insurance premiums were deducted.
- Retirement contributions came straight off the top.
The employer acted as a financial filter. When the check lands, the lender can see what's left to cover a mortgage.
The self-employed borrower gets a closer look. Fannie Mae's guidelines generally call for a two-year history of earnings from tax returns, and the lender runs its own cash flow analysis to find the income it considers stable and continuous.
The other is your job to sort.
before payday.
- Income taxWithheld
- Social Security & MedicareShared with employer
- Benefits & retirementPayroll deductions*
What lands is already net of payroll deductions.
The obligations follow.
- Income taxYours to set aside
- Social Security & MedicareBoth shares are yours
- Benefits & retirementYours to fund
A gross business receipt is not personal spending money.
Illustrative comparison. *Benefits and retirement deductions depend on the employer and elections. Net pay still has household bills to cover.
Why can write-offs shrink what you can borrow?
A client's payment clears, and the full deposit lands in your account. It feels like a big month.
To a lender, it isn't income yet. Nobody withheld your income tax. Nobody paid your self-employment tax. Nobody covered your overhead or your insurance.
Then there's the tax return. Like any smart business owner, you claim every legitimate deduction to keep your taxable income down.
Here's an illustrative year. You bring in $150,000 in revenue. In your head, after operating costs, you clear about $100,000 to live on. After every deduction, your return shows $38,000 of net profit.
The lender starts from the return. Fannie Mae's cash flow worksheet allows certain adjustments, including adding back depreciation and business use of your home. Everyday write-offs, like your phone, travel and client meals, stay subtracted.
You can tell the loan officer you really take home more than the return shows. The lender can't simply take your word for it. The bank has to work from income it can document, with the adjustments its lending rules allow.
So the write-offs that lowered your tax bill can lower the loan you qualify for. Until expenses, write-offs and taxes are accounted for, a deposit isn't a paycheck.
The lender needs the records.
 Illustrative annual figures
These are three perspectives on the article's example, not a step-by-step reconciliation. The $38,000 is reported net profit, not a calculated loan limit. Allowed adjustments, such as depreciation and business use of the home, still matter. Fannie Mae Form 1084.
Where does a deposit actually go?
When a deposit lands, it looks like one big payday. You aren't the only one with a claim on it.
- The business takes its cut first: software subscriptions, the phone line, insurance, professional tools. The costs of keeping the lights on.
- The government takes both halves: as an employee, your employer paid half of your Social Security and Medicare taxes. Self-employed, you pay both, a combined self-employment tax rate of 15.3%, on top of regular income tax.
- Your safety net comes out of pocket: no company health plan, no 401(k) match, no paid sick days or holidays, and no severance if a project falls through.
By the time everyone else is paid, what's left is a lot smaller than what hit your account.
What happens in a month you don't bill?
And that's when things are going well.
An employee with paid leave can take a week off or catch the flu, and the paycheck still arrives. For you, one slow season, one late-paying client or two weeks between projects can drop your income off a cliff.
Your software doesn't give you a discount. Your health insurance doesn't take the month off. Your mortgage doesn't shrink.
A good month makes you feel invincible. A slow month shows you who's carrying the company.
What do owners carry that employees don't?
Business ownership gets sold as freedom. What gets left out is the weight of the legal, financial and moral responsibility.
When you run a business, you eat last. Your biggest client can be sixty days late on an invoice, or sales can dry up for a quarter, and still:
- Vendors expect their invoices paid on time.
- Suppliers want payment for materials.
- Filing deadlines and labor rules don't pause.
- And payroll can't wait.
Employees have to be paid for the work they've done, whether or not the business made money. If cash runs short, you can't ask your staff to wait. Owners cover it from personal savings, from credit cards, or by cutting their own pay to zero. It's why you hear founders say, "I haven't taken a paycheck in six months."
An employee trades upside for a steadier paycheck. The owner takes on the downside, and gets paid after everyone else.
Payroll cannot.
Same $30,000 invoice. Same bills. Change when the client pays.
The invoice still pays $30,000. But the business needs $10,000 from somewhere else before it arrives.
Fictional business. Bills leave before a same-day payment arrives.
See the cash movements
| Day | In | Out | After both |
|---|---|---|---|
| Day 0 | $0 | $0 | $20,000 |
| Day 30 | $0 | −$15,000 | $5,000 |
| Day 60 | $30,000 | −$15,000 | $20,000 |
Separate illustrative business: $20,000 opening cash, one $30,000 invoice, and $15,000 of scheduled business outflows on days 30 and 60. No other receipts, owner pay, new borrowing or financing costs. A negative position is a funding gap, not money available to spend. This is a timing example, not a reserve recommendation.
Can you hand off the bookkeeping?
On top of all that, you can't take your eye off the ball.
Once owners hire an office manager, a bookkeeper or an accountant, it's tempting to hand the money side off completely and focus on the product or the clients. Hiring help moves the work off your desk. The responsibility stays on it.
Here's what that looked like for one Hawaii business.
In October 2025, Hawaii News Now reported on the owner of Dave's Ice Cream, a beloved local business. He says his bookkeeper, hired in 2019, wrote herself 27 company checks between December 2019 and March 2022 while failing to pay employees' payroll taxes, and hid IRS notices from him. At the time of the October 2025 report, she was under criminal investigation and had not been charged.
It came to light in 2024, when a tax lien arrived demanding more than $1 million. The owner borrowed $800,000 against his home to cover taxes and penalties, and paid off the full $1.2 million within five months. The business survived.
The lien came to the owner. The taxes were the business's to pay, and he paid them.
For an owner, someone else's mistake or misconduct can put years of work at risk.
The owner carried the cost.
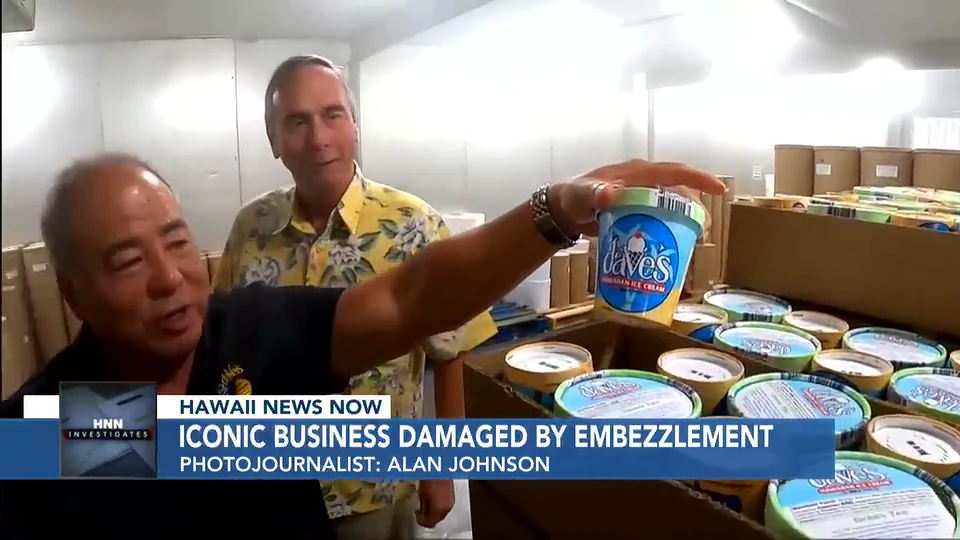 Hawaii News Now · October 6, 2025
- 2019Bookkeeper hired
- 2024Tax lien arrives
- Within five months$1.2 million paid
Amounts and allegations attributed to the owner in Hawaii News Now's October 2025 report. The $800,000 helped fund the $1.2 million payment; these amounts are not added together. The report said the bookkeeper had not been charged. Image: Hawaii News Now / Gray. Read the original report.
Does this mean you shouldn't work for yourself?
No.
The upside, the autonomy and the impact of building your own business are real. But the income is bigger on paper than in practice, and you can't take your eye off the numbers.
You don't have to do the bookkeeping yourself. As the owner, you do have to know what's actually yours before you spend it.
Your next step
Keep your eyes on the whole field. The free Debt Clarity Workbook puts every income source, every fixed and variable cost, and every debt with its Cash Flow Index in one view, so you can see your real bottom line before you spend against it.
Set aside about thirty minutes and plug in your numbers. Get the free Debt Clarity Workbook.
And if you'd rather work through your numbers with someone who does this every day, apply for a free first call. 15 minutes, no fee.
Sources: Hawaii News Now, "Beloved Hawaii business survives costly embezzlement," Daryl Huff, October 6, 2025, https://www.hawaiinewsnow.com/2025/10/07/beloved-hawaii-business-survives-costly-embezzlement/ · IRS, "Self-employment tax (Social Security and Medicare taxes)," https://www.irs.gov/businesses/small-businesses-self-employed/self-employment-tax-social-security-and-medicare-taxes · Fannie Mae Selling Guide, B3-3.5-01, "Underwriting Factors and Documentation for a Self-Employed Borrower," https://selling-guide.fanniemae.com/sel/b3-3.2-01/underwriting-factors-and-documentation-self-employed-borrower · Fannie Mae, Cash Flow Analysis (Form 1084), https://singlefamily.fanniemae.com/media/7746/display
Illustrative examples throughout, except the reported case, which is from Hawaii News Now. Figures are for illustration and are not predictions of individual results. Educational content only. This does not constitute financial, tax, or legal advice.